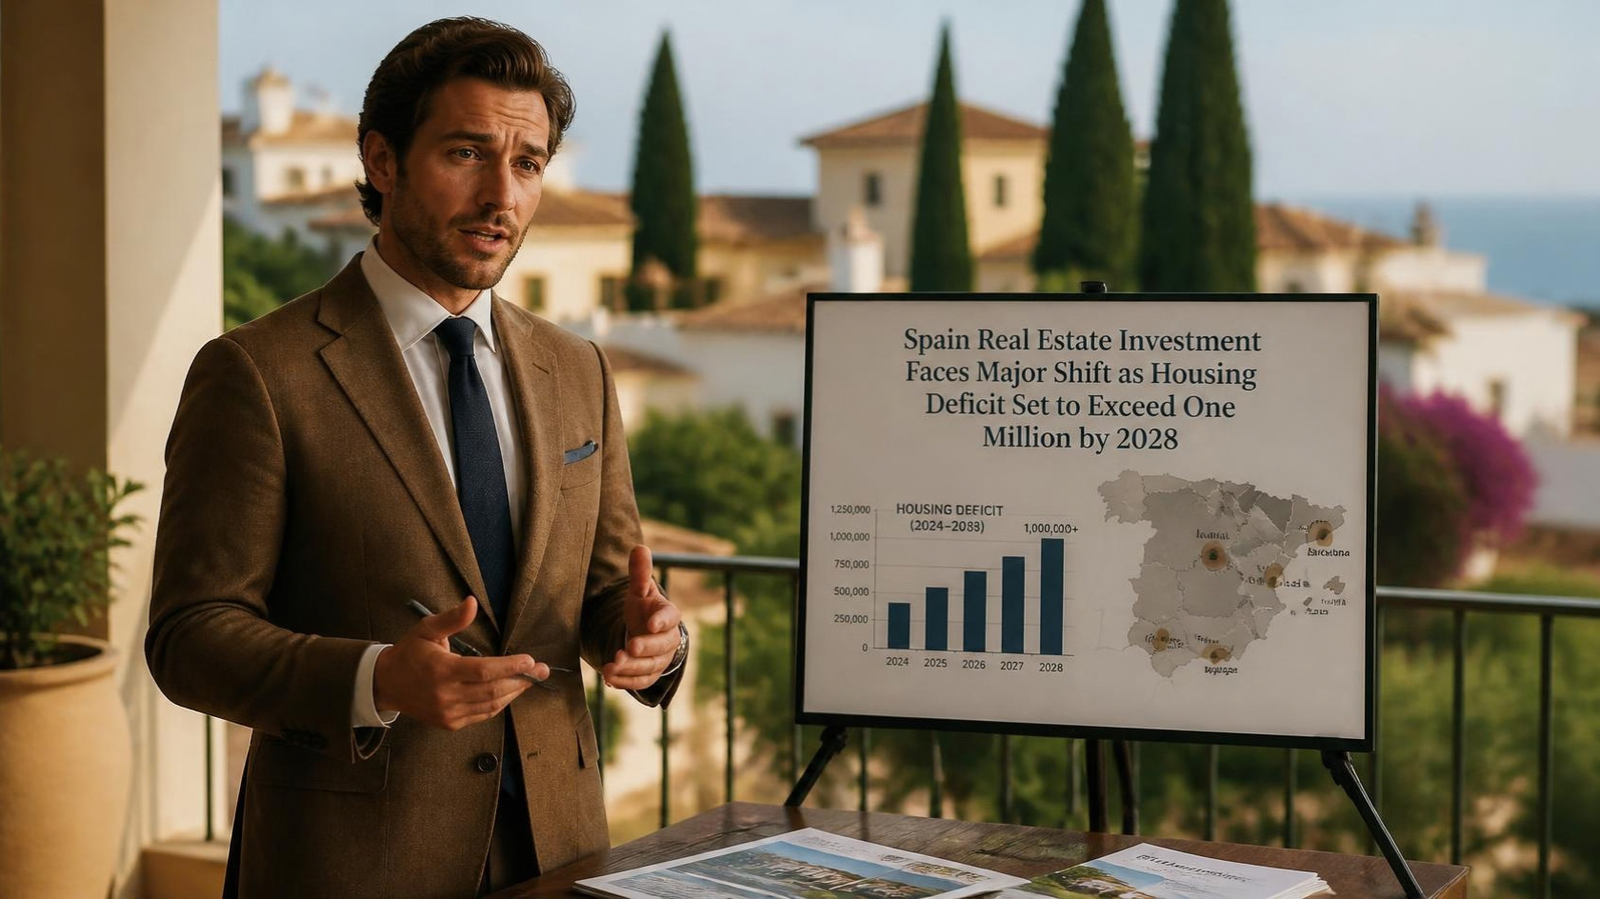
Spain real estate investment is at a turning point. Bank of Spain warns the housing deficit will surpass one million by 2028, with soaring property prices and affordability issues shaping the future for investors and buyers.
Spain’s Looming Housing Deficit Surpasses One Million: The Future of Real Estate Investment and Affordability
A Pivotal Moment in Spain’s Housing Market
Spain’s real estate investment landscape is confronting a turning point, according to the latest warning from the Bank of Spain. As the institution estimates a housing deficit exceeding one million homes by 2028, concerns over skyrocketing prices, accessibility, and investor strategies are coming to the forefront. Real housing prices have surged to levels comparable to the pre-crisis peak of 2005, and the widening gap between household incomes and property prices is pushing home ownership further out of reach for many — especially young people and new residents.
In this comprehensive analysis, we delve into the data and drivers underlying Spain’s escalating housing deficit, explore the repercussions for real estate investors and first-time buyers, and outline potential strategies for navigating one of Europe’s most dynamic — yet challenging — property markets.
The Bank of Spain’s Stark Warning: A Growing Housing Shortfall
The Estimates
On the heels of the 2026 Forbes Economic Summit, Soledad Núñez, Deputy Governor of the Bank of Spain, presented sobering statistics: since 2021, Spain has amassed a negative housing balance of approximately 755,000 homes. If current trends persist, the deficit could grow by an additional 300,000 units between 2026 and 2028, pushing the total shortfall over one million.
Núñez’s remarks put the spotlight on a rapidly widening gap between supply and demand — a structural challenge that, left unaddressed, could have long-term consequences for Spain’s economy, social cohesion, and its attractiveness as a destination for real estate investment.
Housing Prices Outpacing Incomes
Compounding the shortfall is the acceleration of real housing prices. Since 2026, these have risen at their fastest pace in two decades, now mirroring the frothy heights of 2005, just before Spain’s infamous housing bubble burst. According to Bank of Spain figures, while Spanish disposable income has multiplied by 1.8 since 1980 (compared to just 1.6 across the Eurozone), property prices have soared by a factor of 3.5 — nearly double the 1.8 observed in the broader European Monetary Union.
The result is a growing mismatch: the effort, or “esfuerzo”, required to buy a home in Spain is increasing at a rate that far outstrips household earning power.
Understanding the Drivers: Why Is Spain Facing a Housing Deficit?
To make sense of the current crisis, it’s essential to examine the underlying causes:
1. Undersupply of New Construction
Since the global financial crisis of 2008, Spain’s homebuilding industry has never fully recovered. Years of sluggish construction and unresolved bureaucratic bottlenecks have severely limited the rate at which new housing is being brought to market. This chronic undersupply, even as demand rebounds, has laid the groundwork for the present deficit.
2. Demographic Changes
Spain’s demographics are also shifting. Young professionals, emerging from a decade-long period of economic instability, are now seeking to form households, while international migration is contributing to population growth in metropolitan areas. New residents — both from inside and outside Spain — put additional pressure on housing inventories.
3. Foreign Investment and Second-home Demand
Spain remains one of Europe’s prime destinations for foreign property buyers, particularly in coastal regions and major cities like Madrid and Barcelona. The high demand from international investors and wealthy second-home buyers intensifies competition, exacerbating shortages for local first-time homebuyers.
4. Urbanization
Like much of Europe, Spain is experiencing accelerated urbanization. Rural depopulation and job concentration in cities concentrate demand for housing in already robust urban centers, while regional disparities persist.
5. Financial Policy and Mortgage Access
Although interest rates in the Eurozone have remained relatively low in recent years, tightening financial conditions or sudden shifts in policy can quickly make mortgages less accessible — especially impacting those at the margins of the market.
The Affordability Crisis: Who Is Hit Hardest?
The housing deficit’s most acute consequences are felt by young people, low-income families, and new residents.
Young Spaniards and First-Time Buyers
Despite the country’s economic growth post-pandemic, youth unemployment remains above the European average, and wage growth for younger cohorts lags behind property price inflation. The “effort rate” — the percentage of income required to service a mortgage — has breached historical norms, pushing many potential buyers permanently into the rental market or extended periods living at home.
New Residents and Immigrants
Spain’s appeal as a destination for work and lifestyle continues, but new arrivals find themselves facing limited options. Language barriers and lack of established credit histories further hinder their ability to secure decent accommodation, intensifying competition in already tight markets.
Low- and Middle-Income Households
The widening affordability gap is not exclusive to young people. With rents rising alongside purchase prices, a growing share of Spain’s population is now “housing cost-burdened”, spending more than 30% of their income on accommodation — a level that, if sustained, undermines financial stability and social mobility.
Regional Analysis: Where Is the Deficit Most Severe?
While Spain’s housing shortage is a national crisis, some regions are hit harder than others.
Madrid and Barcelona
Spain’s two largest metropolitan areas, Madrid and Barcelona, are the epicenters of the housing crunch. Robust job markets attract domestic and international talent, while high demand from foreign buyers has further driven up prices. Both cities face significant challenges in expanding affordable housing stock, with bureaucratic delays and land scarcity hampering new projects.
Mediterranean Coast and Balearic/Canary Islands
Regions such as the Costa del Sol, Costa Blanca, and island groups like the Balearics and Canaries have seen housing deficits amplified by tourism and demand for second homes. Here, local populations are sometimes priced out by international buyers seeking vacation properties.
Regional Disparities
In contrast, many rural and interior regions continue to contend with depopulation, leaving thousands of homes vacant but often in areas with weak job markets and limited amenities.
Investor Perspective: Challenges and Opportunities for Spain Real Estate Investment
Despite the concerning trends, Spain’s real estate market continues to offer a mix of risks and rewards.
Short- to Medium-Term Risks
- Affordability Constraints: High prices and limited supply can choke off demand, especially among local buyers, increasing the risk of market correction.
- Regulatory Uncertainty: Possible interventions to control rents, tax foreign buyers, or accelerate public housing could alter the investment calculus.
- Bubble Risk: Fast-rising prices, if detached from fundamentals, risk repeating the excesses of the 2008 bubble.
Long-Term Opportunities
- Demographic Tailwinds: Spain’s growing population and urbanization trend promise sustained demand in prime markets.
- Rental Yield Potential: Tight supply favors landlords, especially in high-demand cities.
- Urban Renewal: Investment in regeneration projects and affordable housing can offer both solid returns and social impact.
Strategies for Investors
- Focus on High-Need Segments: Student accommodation, affordable rentals, and multifamily housing are likely to remain undersupplied.
- Geographic Diversification: While Madrid and Barcelona dominate headlines, emerging cities like Valencia, Malaga, and Bilbao are gaining investor interest.
- ESG and Sustainability: Projects with strong environmental and social credentials are increasingly favored by both investors and regulators.
Policy Response: What Are Authorities Doing?
Addressing such a formidable housing deficit demands multi-pronged initiatives:
Streamlining Permitting and Construction
Government pledges to reduce red tape and accelerate housing starts are critical. Greater incentives for private developers to build affordable housing, in tandem with streamlined permitting, are needed to address the bottleneck.
Public Housing Expansion
National and regional authorities have announced plans to ramp up social housing, using innovative financing models and public-private partnerships. However, delivery timelines remain uncertain, and past programs have grappled with delays and cost overruns.
Regulation of Short-term Rentals
Local governments, especially in tourist hotspots, are increasingly regulating Airbnb-style short-term lettings, seeking to balance economic benefits with the need to restore long-term housing stock.
Support for Young and Vulnerable Buyers
Measures such as subsidized mortgages for first-time buyers, rent-to-own schemes, and targeted grants feature in many regional plans but have yet to deliver a transformative impact.
International Context: How Does Spain Compare?
While Spain’s housing crisis is severe, it is not unique. Across Europe, rising home prices and rental costs have provoked protests, policy interventions, and calls for reform.
- Germany: Chronic undersupply in major cities like Berlin has led to rent controls and debates over nationalization of large landlords.
- France: Paris faces a perennial shortage of affordable homes, with government efforts to limit foreign investment and increase public housing.
- UK: London’s affordability crisis is among the world’s worst, prompting government schemes and a surge in Build-to-Rent investment.
Yet, Spain’s pace of housing price growth—outstripping increases in both household income and Eurozone peers—marks it as a particular hotspot for investors and policymakers.
The Road Ahead: Scenarios for the Spanish Property Market
1. Market Adjustment Scenario
If price increases prompt a demand slowdown, homebuilders may catch up, stabilizing the market. Investor returns, particularly in overheated segments, may normalize.
2. Policy-Driven Relief
Major public investment in affordable housing and rental market reforms could alleviate pressure, improving access for young people and residents. However, the scale of intervention required is vast.
3. Continued Shortage
Absent decisive action, housing deficits may worsen, driving further price increases, widening inequality, and stoking social tensions. This scenario presents both risks and select opportunities for patient, value-oriented investors.
Navigating a Transforming Market
Spain stands at a crossroads. The country’s projected housing deficit of more than one million units by 2028 reflects a confluence of demographic trends, supply constraints, and soaring demand from both domestic and foreign buyers. For real estate investors, the landscape is fraught with challenges — but also rich in opportunity, particularly for those who adapt to shifting dynamics and place affordability and sustainability at the center of their strategies.
The response of policymakers, developers, and investors over the next few years will shape not only the trajectory of Spain’s real estate market but also the opportunities available to Spaniards and international buyers alike. Whether Spain’s housing market returns to a sustainable equilibrium — or repeats the painful cycles of the past — remains to be seen. What is clear is that the stakes for investment, policy, and society have rarely been higher.
References:
- Bank of Spain: Housing Market Reports
- Forbes Economic Summit 2024
- Eurostat: Eurozone Property and Income Data
- Spanish National Institute of Statistics (INE)
Tags:
Spain Real Estate Investment, Spanish Housing Market, Housing Deficit Spain, Property Investment, Spain Housing Prices, Bank of Spain, Real Estate Trends, European Housing Market, Youth Housing Crisis
Lorem ipsum dolor sit amet, consectetur adipiscing elit. Ut elit tellus, luctus nec ullamcorper mattis, pulvinar dapibus leo.