Discover the latest trends in repossessed homes for sale in the UK. House Buyer Bureau reveals a 30% price reduction on repossessed properties, with almost 1,500 on the market. Find detailed regional insights and expert guidance.
Repossessed Homes for Sale in UK Take a 30% Price Hit: Regional Breakdown, Causes, and Buyer Opportunities
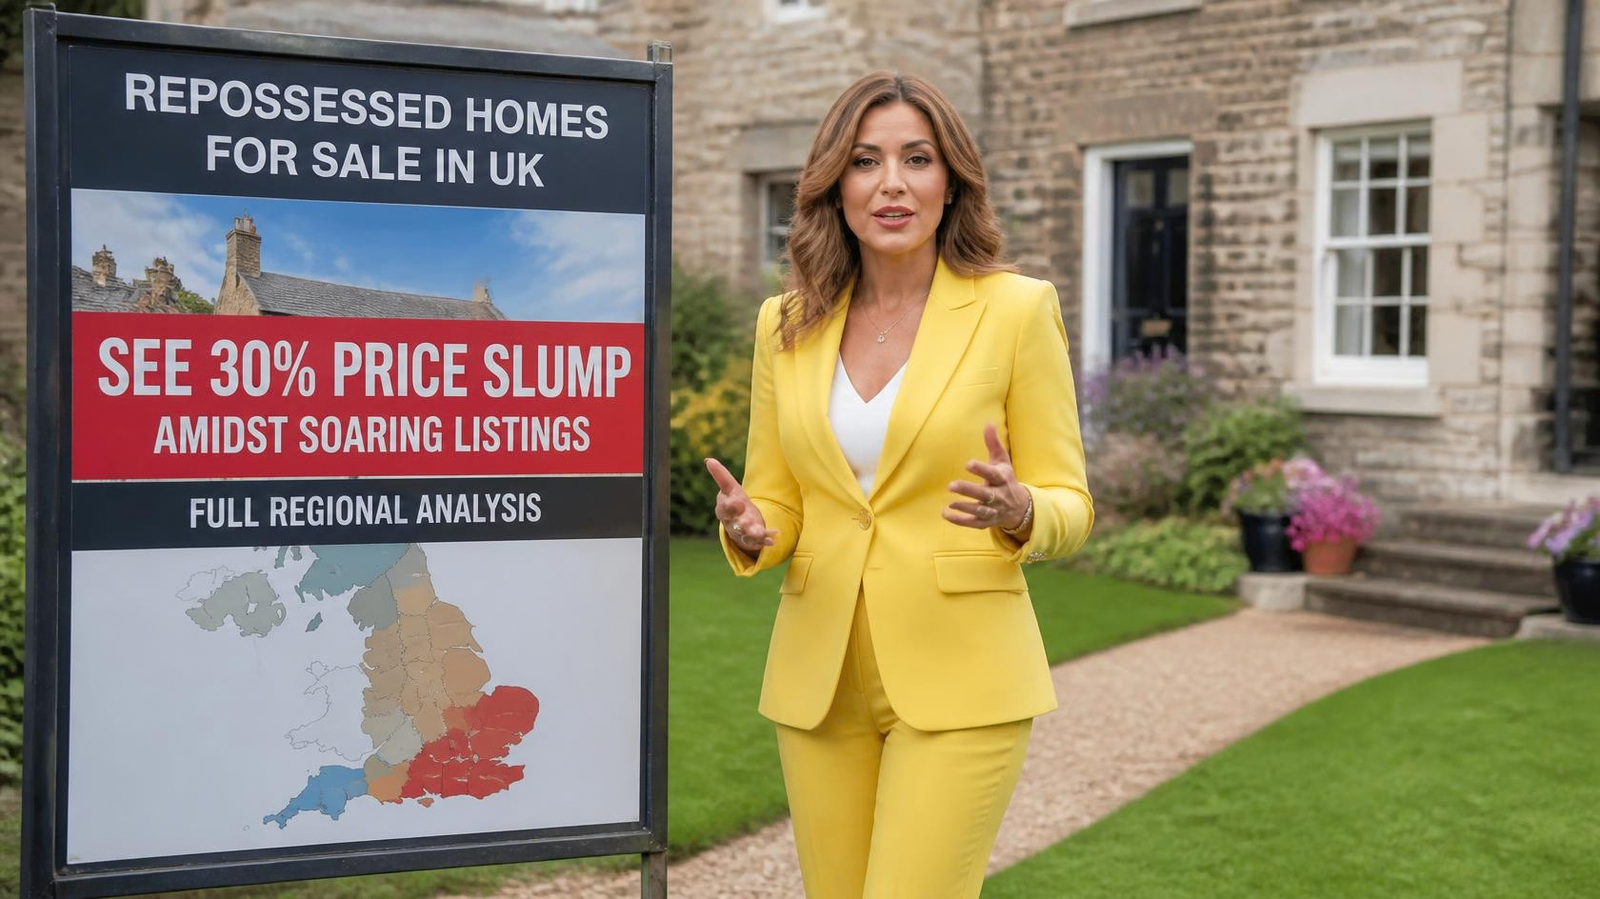
The UK property market is experiencing a striking trend as repossessed homes for sale witness a dramatic slump in prices, with nearly 1,500 properties now listed at an average of 30% below the prevailing market rates. According to a comprehensive analysis by the House Buyer Bureau, this shift presents unique challenges for sellers, while offering rare opportunities for buyers seeking value in an otherwise expensive market.
Surge in Repossessed Homes for Sale in the UK: The Numbers Explained
Housing repossession is a growing reality amidst the UK’s challenging economic conditions. The House Buyer Bureau reports that there are currently 1,442 repossessed homes for sale across England. These properties, repossessed by lenders after borrowers default on mortgage payments, are being listed at prices significantly below their local market averages.
- Average price of a repossessed property in England: £177,157
- Wider national average house price: £254,460
- Average price reduction: -30.4%
The largest concentrations of these bargain-priced homes are found in the South East and North West, each accounting for 18% of the national total. The East of England follows with 14%, and Yorkshire & Humber accounts for 11% of all repossessed listings.
Regional Breakdown: Where Are Repossessed Homes for Sale Most Common – and Cheapest?
London
London’s housing market has long been a bellwether for national trends, and the capital is seeing repossessed homes for sale at the deepest price cuts. The average offer price for repossessed homes in London is -37.9% below the city-wide average property value. This dramatic discount reflects both the premium typically associated with London housing and the urgent nature with which lenders wish to dispose of repossessed stock.
South West
The South West region also sees a notable price adjustment. Here, repossessed homes are marketed at 32.9% below regional averages. This is significant, especially given the recent popularity and price inflation of South West properties during and post-pandemic, as many buyers sought more space and rural living.
Yorkshire & Humber, North West & West Midlands
Other areas seeing substantial price cuts include:
- Yorkshire & Humber: -31.7%
- North West: -31.2%
- West Midlands: -30.1%
These regions demonstrate how widespread the trend is: whether in the north or south, repossessed homes are consistently marketed far below the comparable average home.
Why Are Repossessed Homes Sold at such Large Discounts?
Fast Sales Are Key
When banks or lenders repossess homes, their primary motive is quick liquidation. Every month a property remains unsold incurs costs for maintenance, security, and administration. Selling at a significant discount ensures a faster transaction.
Condition and Marketability
Many repossessed homes require refurbishment or repairs, having suffered from years of neglect or lack of regular maintenance. This can dissuade mainstream buyers, and as a result, prices are lowered to entice investors or owner-occupiers willing to renovate.
Less Desirability
Repossessed listings may not always benefit from staged marketing or high-quality photography, further reducing perceived value. A buyer may also face procedural complexities compared to a typical home purchase (for example, stricter timescales and viewing restrictions).
Macro-Economic Factors
Soaring inflation, rising interest rates, and the cost of living crisis have created financial distress for many homeowners across the UK. This in turn has led to more repossessions – and consequently, more pressure on lenders to liquidate these assets quickly.
Who’s Buying Repossessed Homes for Sale in the UK?
The UK market for repossessed properties comprises a diverse mix of buyers:
- Cash Buyers and Investors: These buyers are the most active in the repossessed segment, often seeking below-market deals for investment or resale after renovation.
- First-Time Buyers: With mainstream prices often out of reach, savvy first-time buyers turn to repossessed options for a foot on the property ladder.
- Self-Builders and Renovators: Those looking for a project, including professional renovators, may see value in upgrading a repossessed home and benefiting from the equity uplift.
How to Buy a Repossessed Home in the UK: Step-by-Step
- Search for Listings
Repossessed homes are frequently sold via estate agents, auction houses, or property portals highlighting ‘mortgagee in possession’ or ‘bank repossession’ properties. Specialist sites often compile lists of repossessed homes for sale in the UK. - Finance Preparation
Buyers must have their finances in place—preferably cash or a mortgage ready—since lenders often stipulate tight deadlines for completion to minimize their losses. - Survey and Legal Checks
Repossessed properties are frequently sold “as seen”, so an independent survey is vital to assess structural condition and any hidden issues. Buyers should appoint an experienced conveyancer familiar with repossessed sales. - Submit an Offer
Competition can be fierce, especially at the lower end of the market. Offers are not always accepted on a first-come, first-serve basis, and lenders may continue to market a property until contracts are signed. - Speed is Essential
If your offer is accepted, proceed rapidly with legal formalities—delays can cause deals to fall through, or the property to be remarketed if another higher offer emerges.
Advantages and Disadvantages of Purchasing a Repossessed Home
Advantages
- Significant Savings: The most obvious lure is price – paying up to 30% less than market value can generate instant equity and make ownership affordable where it otherwise wouldn’t be.
- Potential for Value-Add: Buyers with the readiness and funds to renovate can realize even greater value through improvements.
Disadvantages
- Condition Risks: Repopsessed properties may require costly repairs, and issues can be hidden.
- Transaction Uncertainty: Lenders can accept higher trailing offers even after initial acceptance, leading to gazumping.
- Limited Background Information: Disclosure about the property’s history and condition may be lacking.
The Economic Context: Why are Repossessions Rising?
Inflation and Interest Rates
The Bank of England’s repeated rate hikes since 2022 have placed greater financial pressure on mortgage holders, particularly those on variable or tracker products. The spike in monthly repayments has pushed many households into arrears.
Cost of Living Squeeze
Rampant inflation has pushed household costs to record highs, stretching family budgets and making mortgage payments untenable for some. The culmination of these pressures has contributed to an uptick in repossessions, particularly in already economically-vulnerable regions.
Pandemic Legacy
The COVID-19 pandemic, job losses, and furlough periods led many households to fall behind on mortgage payments, only for lender forbearance to end in late 2021 and 2022, ushering in a new wave of repossessions.
Current State of the UK Property Market – and Its Impact on Future Repossessions
The UK property market as a whole continues to show signs of cooling after a period of extreme price growth. While demand remains high in certain segments and regions, affordability has reached its limits for many. The net result is an increase in properties via orders for repossession appearing on estate agents’ books.
Add to this scenario the ongoing cost-of-living pressures and persistent economic uncertainty, and experts suggest that the current figure of about 1,500 repossessed homes for sale in the UK could rise further in the coming year.
Government and Lender Responses
Support Schemes
The UK Government and some lenders have implemented support schemes to help struggling homeowners, from mortgage holidays to tailored repayment plans. However, for many who have exhausted their options, repossession remains a last resort.
Reforms and Safeguards
The Financial Conduct Authority (FCA) continues to monitor practices in repo property sales to ensure fair treatment of borrowers and transparency for buyers.
Expert Opinion: Is Now a Good Time to Buy a Repossessed Home?
Specialists in property investment have suggested that now may be an excellent opportunity for buyers, but caution is crucial.
Navigating the Surge in Repossessed Homes for Sale in the UK
The current surge in repossessed homes for sale in the UK – priced at up to a 30% discount compared to the wider market – marks a pivotal moment in the ongoing evolution of the British housing sector. For buyers in search of value, now may be a rare window of opportunity. However, informed purchasing, diligent surveys, and rapid action are key to avoiding potential pitfalls. As economic uncertainty endures, the UK repossessed property market is likely to remain both a challenge for families in hardship and a source of affordable housing for those ready to navigate its unique dynamics.
For those considering buying or investing in repossessed homes for sale in the UK, consult with legal and property professionals, and monitor the evolving economic landscape to make the most informed decision.
Frequently Asked Questions About Repossessed Homes for Sale in the UK
Q: Are repossessed homes always the cheapest on the market?
A: Generally, repossessed homes are priced significantly below comparable properties, but buyers must investigate the property’s condition and local demand before assuming a bargain.
Q: Can I get a mortgage to buy a repossessed home?
A: Yes, but lenders may be wary of properties in poor condition. Mortgage approval can be slow, and cash buyers may be favored.
Q: How quickly do I need to move?
A: Speed is vital. Most lenders expect completion within 28 days or sooner.
Q: Will there be issues with utilities or maintenance?
A: Some repossessed homes may have disconnected utilities or neglect-related damage. Surveys and professional advice are advised.
Tags:
repossessed homes for sale in UK, UK property market, house repossession, property prices UK, regional housing market, real estate trends UK, buying repossessed property, affordable homes UK